Mia W.
Senior Writer
October 6, 2026
5 min
read
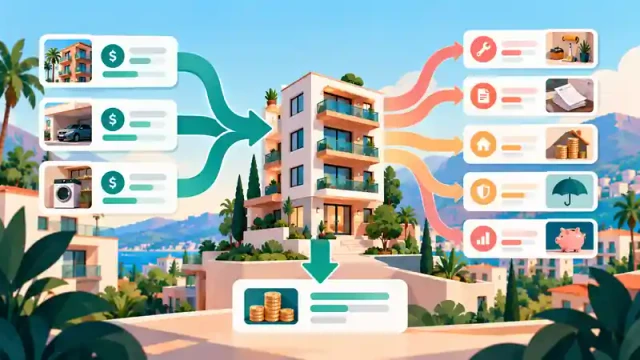
A rental-property cash-flow spreadsheet should answer a simple question:
After the property's actual income and cash expenses, how much cash is left—and where did it go?
The important word is actual.
Do not build the spreadsheet around what you expected to collect. Build it around transactions that actually occurred, while keeping expected rent and future obligations available for planning.
Record each income transaction on a separate row.
DatePropertyUnitTypeAmountOctober 1P0012ARent$1,650October 2P0012BRent$1,800October 3P001—Parking$100
This structure makes it easier to filter by property, unit, transaction type, and reporting period.
Keep partial payments as separate transactions rather than combining them into one monthly total. That preserves the payment history and makes reconciliation easier.
Use a separate table for expenses.
DatePropertyCategoryVendorAmountOctober 4P001PlumbingABC Plumbing$285October 7P001InsuranceXYZ Insurance$140October 12P001AdvertisingLocal Ads$80
This allows you to identify where money is actually going and compare expenses across properties and reporting periods.
Use consistent categories, and retain invoice or receipt references wherever possible.
Consider this example:
ItemAmountRental income collected$5,000Operating cash expenses-$1,500Cash flow before financing$3,500Mortgage payment-$2,000Cash remaining after mortgage payment$1,500
Do not collapse these figures into one number.
The distinction helps you understand whether a property has an operating problem or carries a particular financing structure.
For clarity, the $3,500 figure here is a simplified cash-flow measure before financing, not necessarily formal net operating income. Formal net operating income is calculated using recognized operating-income and operating-expense definitions, generally excluding debt service and capital expenditures.
Mortgage payments also contain principal and interest, which can have different accounting and tax treatment.
A routine repair and a major improvement can have different accounting and tax treatment.
For U.S. rental property, IRS Publication 527 discusses rental expenses, improvements, and depreciation.
Your spreadsheet can include a classification such as:
This preserves the information without pretending the spreadsheet itself has made the accounting or tax decision.
Keep the original transaction amount and supporting documentation, even when a transaction needs further review.
Positive monthly cash flow does not mean a property has no future cash requirements.
A roof replacement, HVAC system, appliances, or major tenant turnover can create a substantial bill.
You can therefore track:
For example, a landlord might set aside $300 per month toward future repairs and replacements.
A reserve contribution is primarily a cash-planning measure. It is not automatically a tax-deductible expense simply because money has been set aside.
Keep reserve planning separate from the property's actual transaction-based cash flow.
A portfolio total can hide a weak property.
Consider this example:
PropertyMonthly cash flowP001+$2,500P002+$2,000P003-$1,800Portfolio total+$2,700
The portfolio still generates positive cash flow, but P003 deserves investigation.
Possible explanations include vacancy, unusually high maintenance costs, low rent relative to expenses, or financing costs.
Always retain a property-level view. A positive portfolio total does not mean every property is performing well.
A spreadsheet is only useful if its records are reliable.
Periodically compare it with:
Investigate differences rather than simply adjusting totals until they match.
For example, a payment recorded in the spreadsheet but absent from the bank statement may have been entered incorrectly, reversed, or recorded in the wrong period.
The spreadsheet should be traceable to the underlying financial records.
Do not stop at:
Did this property make money?
Ask:
What income was collected, what did we spend it on, what financing did we have, and which property generated the result?
That is what makes a cash-flow spreadsheet useful.
Once answering those questions requires reconciling multiple spreadsheets, payment records, and tenant records, a centralized property-management system can become more practical.
RentDoo is designed to help landlords bring core rental operations into one system instead of maintaining the entire workflow manually.
IRS — Tips on Rental Real Estate Income, Deductions and Recordkeeping
IRS — Publication 527: Residential Rental Property